Columbus, Salt Lake City, Reno, Raleigh, Denver, Kansas City, Texas metros

Best Secondary Colocation Markets: Where Capacity Lives in Late 2026 and 2027

A secondary colocation market is a metro outside the crowded hubs like Ashburn, Silicon Valley and Chicago, where power is easier to get and new space often arrives sooner. Going into 2027 that includes the Texas metros, Salt Lake City, Phoenix, Denver and the Carolinas. On our November 2026 price sheet a full 48U rack with 5 kW runs $1,500–1,750 a month in Dallas, Houston, Austin, Charlotte, Raleigh, Las Vegas and Salt Lake City, against $1,600–1,800 in most other markets.

Updated November 2026 · Bob Spiegel, Founder, QuoteColo

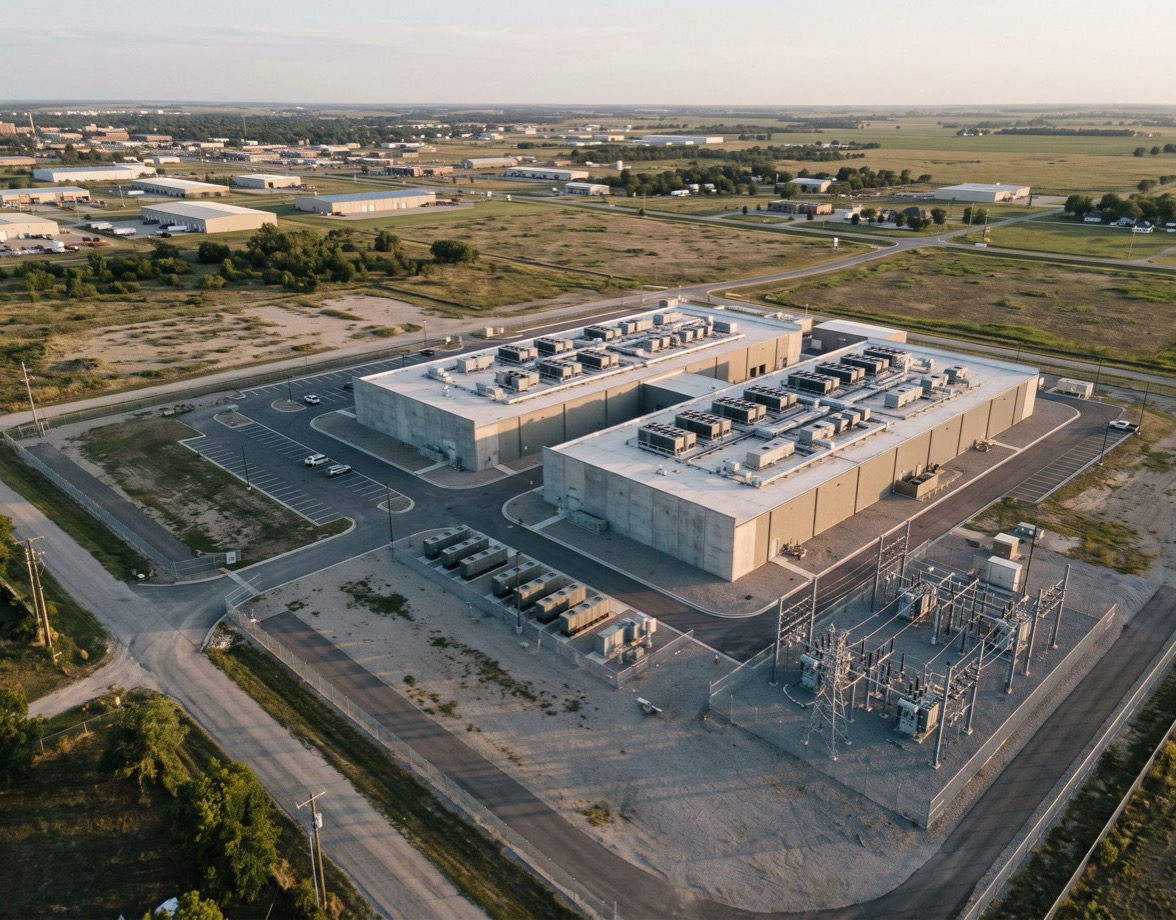
Aerial view of a data center campus and its substation at the edge of a smaller US city, with open land around it
Bob Spiegel

“Tell me what you’re deploying; I’ll come back with real options from a network built over 20 years.”

— Bob Spiegel, Founder, QuoteColo

From our desk, November 2026

$1,500–1,750
Full 48U rack, 5 kW, in Dallas, Houston, Austin, the Carolinas, Las Vegas and Salt Lake City
$1,600–1,800
The same rack in Chicago, NYC, Ashburn, Los Angeles and most other markets
25 of 26
Markets on our sheet with Dallas as a Plan B market
12
High-density listings in Texas, the most of any state

From Bob’s November 2026 price sheet and capacity list (listings, not confirmed offers) and the October 2026 price index (50+ provider responses). Prices are per month, space and power, unless noted.

Primary vs. secondary markets: what you actually get and give up

The tradeoff isn’t quality vs. cost. It’s ecosystem density vs. availability and price.

FactorPrimary markets (Ashburn, NYC/NJ, Silicon Valley)Secondary markets (Columbus, SLC, Reno, Raleigh, Denver)
Power and timelineConstrained; 6–12 month queues in many facilitiesMore available; pre-built capacity is more common
Carrier densityHighest in the countryGood to strong, and growing in most markets
Cloud on-rampsIn-building at most major facilitiesAvailable at leading facilities
12-month termsHarder to find; 24–36 months commonMore available from mid-tier operators

Primary here means CBRE’s eight primary North American markets (Northern Virginia, Dallas-Fort Worth, Silicon Valley, Chicago, Phoenix, New York Tri-State, Atlanta and Hillsboro); every other market is secondary. For most workloads, secondary markets are a genuine option, not a fallback.

The secondary markets that actually have capacity going into 2027

Not all secondary markets are equal. Here’s an honest read on the ones worth a place on your shortlist.

MarketWhy it’s on the listBest for
Columbus / OhioOne of the fastest-growing secondary markets: central US latency, affordable power, new construction.Midwest latency, DR, cost-driven compute
Salt Lake City, UTLow-cost power and a growing carrier ecosystem.Power-cost-sensitive workloads, AI training, West region DR
Denver, COMountain West hub; our November 2026 capacity list shows high-density space in Colorado at $165–250+ per kW, the largest block 2 MW, for Q4 2026.Mountain West reach, mid-size wholesale, air or liquid deployments
Reno / Northern NevadaHyperscale-adjacent campuses next to California, competitive energy costs, no state income tax.California-adjacent workloads at lower cost, wholesale AI
Raleigh / Durham, NCA growing tech ecosystem with Tier III and compliance-certified options, without Northern Virginia pricing.Regulated and government-adjacent workloads, Southeast enterprise

Also worth a look: Austin TX, San Antonio TX, Kansas City MO and Indianapolis IN. We compare them with primary options whenever your location is flexible.

Primary markets with room: Dallas, Phoenix, Atlanta

CBRE counts Dallas-Fort Worth, Phoenix and Atlanta among the eight primary North American markets. They make most Plan B lists because they carry the heaviest new construction outside Northern Virginia, but availability is still tight: CBRE put Dallas-Fort Worth vacancy at 1.8% in Q1 2026, and primary-market vacancy at a record-low 1.4% in H1 2026. We quote them alongside secondary options whenever your location is flexible.

Want these numbers for your own deployment? and we’ll reply with the providers that fit, with their prices.

When a secondary market is the right call (and when it isn’t)

Secondary markets are not a universal substitute for primary markets. Here’s how to think about fit.

Secondary markets work well for

  • Compute-heavy workloads with predictable traffic, such as AI training, batch analytics and data processing. They need power, cooling and a network more than sub-5 ms latency.
  • Disaster recovery and backup, where geographic separation is the point.
  • Cloud repatriation, through a facility with an AWS Direct Connect or Azure ExpressRoute on-ramp.
  • Multi-site deployments: usually only one site in three or four needs primary-market carrier density.

Secondary markets are harder for

  • Trading and other applications that need sub-millisecond paths to specific exchange endpoints.
  • Interconnection that depends on carrier hotels such as One Wilshire, 60 Hudson Street or 350 East Cermak.
  • Network-gravity workloads tied to the peering fabric of one primary market.

Secondary market pricing snapshot: what you actually pay

Secondary markets usually win on availability and timeline first, and often on price. These are the numbers we work from for late 2026 and 2027 deployments.

Planning bands for late 2026 and 2027 deployments

Deployment$/kW/month, space and powerWhat to expect
Under 100 kW$225–250A planning band; small racks and special configurations can differ.
100–500 kW$200–250The footprint many larger providers want right now.
1 MW and up$185–250Plan on 6–12 months, so 2027 blocks are being reserved now. $185 is the build-to-suit low end, not ready-now space.
Near-term listings$190–300Four listings of 200–800 kW on our desk, October 2026. Immediate capacity can price above the band.

QuoteColo price index, October 2026, 50+ provider responses. Planning bands, not market averages; bandwidth, cross-connects, IPs, setup and remote hands can be extra. Single racks are priced per cabinet: a Sacramento-area full rack quoted in August 2026 came to $1,732.50 a month (42U, about 6 kW with A/B feeds, 1 Gbps, 12-month term, $1,000 setup). The index has no separate band for 500 kW–1 MW: those deals are priced individually, and our October 2026 listings of 500–800 kW ran $190–240/kW.

On our November 2026 list, for late-2026 delivery

StateListed power$/kW/monthTermsAvailable
Colorado750 kW$25024 or 36+ months; air and liquidQ4 2026
Pennsylvania200 kW$20036 months; air200 kW listed as available now, non-redundant
Utah800 kW listed$24036 months500 kW listed as immediate; the rest Q4 2026

Space and power. Listings from our capacity list of November 4, 2026, not closed deals; provider names withheld. Listed power is not always one contiguous block, and listings change week to week. Waits for 2027 could be much longer, so reserve early.

Why primary markets aren’t the right default answer for 2027

Most teams start with one of three assumptions. Going into 2027, each one can cost you a quarter.

THE DIY WAY

You target Ashburn because it’s always been the answer

Ashburn remains the richest carrier ecosystem on the East Coast, but new power commitments carry 6–12 month delivery timelines. If you need to be live in the first half of 2027, Ashburn may not get you there.

THE DIY WAY

You target Silicon Valley because your users are in California

Silicon Valley power is scarce and priced accordingly. Reno, or Phoenix among the primary markets, delivers West Coast latency with more capacity available, usually at a lower rate. Round trips to California typically run about 5–20 ms, depending on your endpoints and routes.

THE DIY WAY

You rule out secondary markets because the connectivity isn’t there

That was true a few years ago. Columbus, Salt Lake City and Denver now have mature carrier ecosystems and redundant fiber, with cloud on-ramps at leading facilities.

How it works

You send the specs. We find the options. You decide.

STEP 1

Send your requirements.

Tell us what you're deploying, where you want it, and when you need it. Send the specs you have; we'll help with the rest.

HardwareRacks & kWLocationStart date

Estimates are fine. No perfect RFP needed.

STEP 3

Take the next step. On your terms.

Like the options? Contact the providers directly. Need more detail? Call or email us. We're here to help, not push you.

  • Go directly to the providers you like
  • Ask us questions whenever you need

Get Secondary Market Colocation Options

Free for buyers

Your price is the same as going direct.

All-in estimates by email

From 500+ providers. No sales calls, no long forms.

Trusted service since 2004

5,000+ clients helped.

Your request will be sent securely to QuoteColo.

Why secondary markets are a real strategy going into 2027

Primary vacancy hit a floor.

Many facilities in Ashburn, Silicon Valley and similar markets are full, won’t take your footprint or can’t deliver power in time.

Connectivity caught up.

Leading facilities in Columbus, Salt Lake City and other secondary metros offer cloud on-ramps in the building or through partners.

Plan B is now a standard step.

Experienced teams compare secondary options from the start. We put both in one shortlist whenever your location is flexible.

Case studies

See how we helped teams secure colocation with the right power, pricing, and providers.

Leonard Roszkowski

CEO Elemental Energy Solutions

Problem: Needed to source ASIC servers domestically. Skeptical about working with a new organization.

What we did: Connected them to buyers, sellers, and infrastructure partners across deployments. Removed procurement and logistics overhead entirely.

Result: Rapid organizational growth in a short period. Now uses QuoteColo as an ongoing procurement interface across hardware and infrastructure.

Noel Frutasio

CEO FSN Services and Communications

Problem: Regularly needed colocation space across multiple US states and time zones. Difficult to navigate the market without deep industry knowledge.

What we did: Defined requirements in one meeting, then delivered proposals with multiple carrier and data center options across every target market.

Result: Placed in 4 cities. Contracts signed quickly. Multi-state colocation needs resolved through a single point of contact.

Tim Mandell

DC Mining / MDI Access

Problem: Needed reliable options for crypto mining containers and equipment, along with industry partners who could support real deployment requirements.

What we did: Connected the project with relevant mining infrastructure and equipment resources through the QuoteColo network, simplifying the search and evaluation process.

Result: Gained a clearer path to suitable mining infrastructure, equipment and industry contacts without having to source every option independently.

5,000+

Clients helped since 2004

No Cost

to Buyers

500+

Worldwide providers

Quotes

in 48 h

FAQ — secondary colocation markets

What is a secondary colocation market?

A secondary colocation market is a data center market outside the top-tier primary hubs (CBRE counts eight: Northern Virginia, Dallas-Fort Worth, Silicon Valley, Chicago, Phoenix, New York Tri-State, Atlanta and Hillsboro). Secondary markets typically offer better power availability, faster deployment timelines and often lower pricing, in exchange for somewhat lower carrier density. Markets like Columbus, Salt Lake City and Denver now have mature carrier ecosystems and direct cloud on-ramps that make them viable for most enterprise workloads.

How much cheaper is colocation in a secondary market?

It depends on the market and your size, so compare real quotes side by side. For late 2026 and 2027 deployments, QuoteColo’s price index (October 2026, 50+ provider responses) puts space and power at $225–250 per kW per month under 100 kW, $200–250 for 100–500 kW and $185–250 for 1 MW and up. These are planning bands, not market averages. Bandwidth, cross-connects, IPs, setup and remote hands can be extra. Near-term listings on our desk ranged $190–300 in October 2026. On our October list, for example, Colorado has 750 kW at $190–225/kW and Pennsylvania 500 kW at $200/kW for late 2026.
What do I give up by choosing a secondary market?

The main tradeoff is carrier density. Primary markets like Ashburn and One Wilshire have hundreds of carriers, cloud providers, and IX points in-building. Secondary markets have fewer carriers on-net, though leading facilities in Columbus, Salt Lake City and Denver have enough diversity for most enterprise workloads. For latency-sensitive financial applications or carrier-hotel-dependent interconnection strategies, primary markets are often still the right answer.

Which secondary market is best for AI and GPU workloads?

For AI training and compute-heavy workloads where $/kW matters and location is flexible, the Pacific Northwest (Washington, Oregon), Salt Lake City, Texas (San Antonio, Austin), and the Carolinas offer the best combination of power pricing and available capacity. Columbus and Reno are strong alternatives; among primary markets, Phoenix and Dallas are worth quoting alongside them. QuoteColo matches AI deployments to secondary markets based on power density capability and cooling type, not just location.

Is the connectivity in secondary markets good enough for production workloads?

For most production workloads, yes. Columbus, Salt Lake City and Denver have cloud on-ramps and carrier-neutral options at leading facilities. What they don’t have is the same density of carrier options as Ashburn or One Wilshire. If your workload needs cross-connects to specific carriers only present in primary-market carrier hotels, verify which secondary-market facilities have those carriers on-net before committing.

Which US secondary markets have the most available capacity right now?

Going into 2027, capacity is easiest to find in secondary markets such as Columbus/Ohio, Salt Lake City, Reno, Raleigh/Durham, Denver and the Texas secondary metros (San Antonio, Austin). Kansas City and Indianapolis are also underrated for central US latency and cost. Among primary markets, Dallas, Phoenix and Atlanta have the most new construction, though vacancy there is near record lows. Availability changes week to week, so we check which market has capacity for your power requirement and timeline before you commit.

Get 2–4 qualified options in 48 hours

Free for buyers

Your price is the same as going direct.

You will get all-in price estimates by email

From 500+ providers. No sales calls, no long forms.

Trusted service since 2004

5,000+ clients helped.

Your request will be sent securely to QuoteColo.