Public listings and announcements
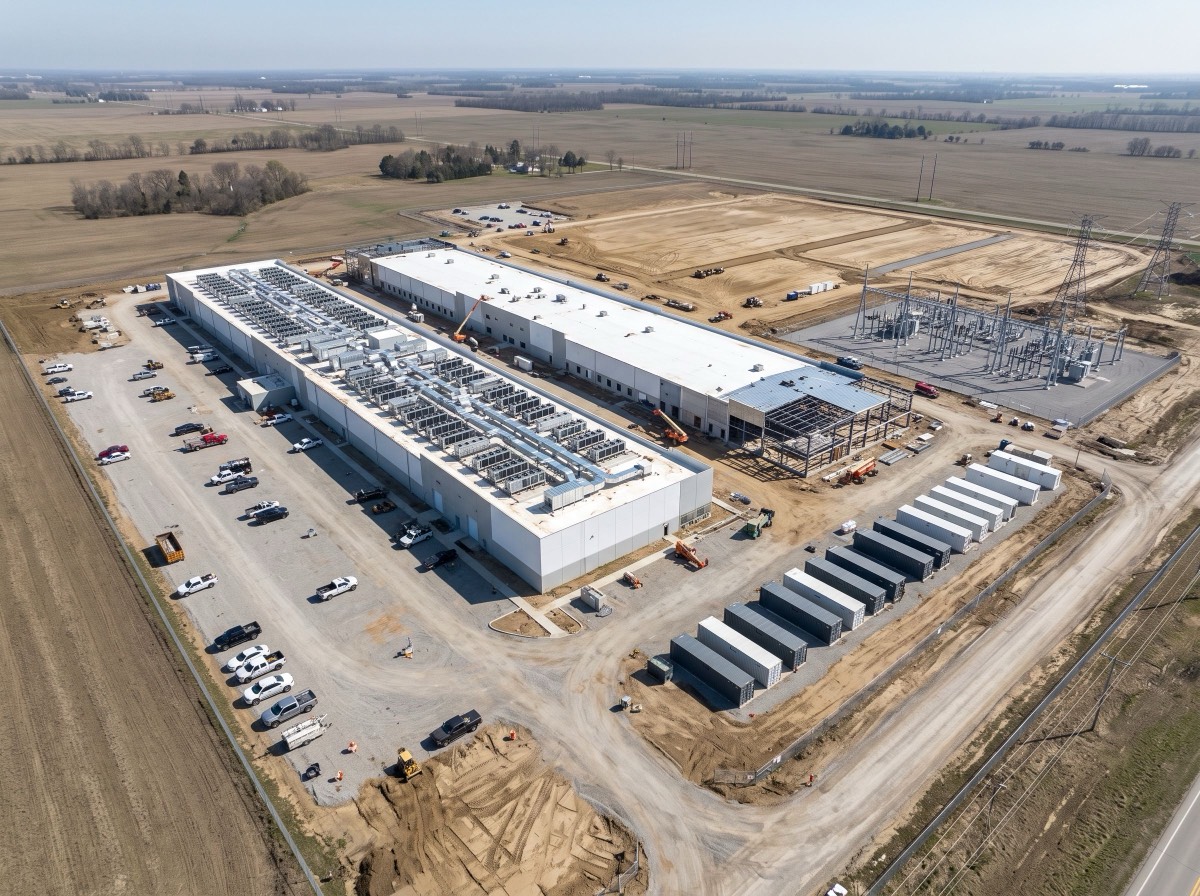
Large campuses get announced once they’re pre-leased: more than 80% of primary-market capacity under construction already is (CBRE, H1 2026).
For neo clouds and AI infrastructure developers
Tell us the MW, the date and the power your lender will accept. We’ll send powered sites and capacity that can hold that date.
Get my optionsFree for you. Bob Spiegel answers MW inquiries: (888) 400-5732.
“At 10 MW and up, I check the power first: what’s energized, what’s only a study, and what date the utility will commit to. Send me your MW and date, and I’ll tell you which sites can hold it.”
— Bob Spiegel, Founder, QuoteColo
Referral service since 2004
Providers, including regional operators
For buyers: providers pay us
Sites and capacity on our desk
Real sites and capacity from our marketplace, read on 29 October 2026. They show shape and pricing, not current availability: listings change week to week, so call (888) 400-5732 for what’s open now.
Under 1,500 MW
left to pre-lease across the eight primary North American markets
80%+
of capacity under construction already pre-leased, up from 74.3% a year earlier
+8.3%
asking rents for 3–10 MW in H1 2026, the fastest rise of any size band
1.4%
vacancy across the primary markets, 0.2% in Northern Virginia, with a record 7,481 MW under construction
CBRE, North America Data Center Trends H1 2026, released 27 August 2026. Primary markets: Northern Virginia, Dallas-Fort Worth, Silicon Valley, Chicago, Phoenix, New York Tri-State, Atlanta and Hillsboro. With most new capacity pre-leased before it is finished, the sites that matter at 10 MW and up are the ones that aren’t advertised.
Two sites can advertise the same 50 MW and be years apart. We ask which of these each site actually has, and mark it on your shortlist.
Power is live at the site today. The only status that supports a near-term date on its own.
The utility has committed capacity in writing, with a delivery date. Check the date and any upgrades it depends on.
The utility has studied the load. Useful evidence, but not a commitment.
A request is in the utility’s queue. The timing is the utility’s, not the seller’s.
An advertised MW figure. Treat it as a question, not a number. A nearby substation is not proof of deliverable power.
At this scale the power structure is not a technical preference. It decides who will finance the site and who will sign for the capacity.

Four steps. The first is the only one that needs anything from you.
MW target, the date it has to be live, front-of-meter or behind-the-meter, and offtaker status. No company name, entity forms or financials to start.
Usually two: what you mean by powered land, and whether you’re the end client or acting for one.
Matched sites by email: capacity, energization status, structure and terms, with any credit condition marked. Plus our marketplace list, which changes as listings do.
Name the listings you want and we introduce you by email, direct to the site owner, developer or operator. You negotiate; we stay reachable.
At 10 MW and up, most of what you can find yourself is already spoken for, and the rest takes an NDA before anyone names a date.
Large campuses get announced once they’re pre-leased: more than 80% of primary-market capacity under construction already is (CBRE, H1 2026).
Formal RFPs across regions, with fees and a process to match. Right for a multi-region 50 MW+ program; slow for a dated first phase.
NDAs and qualification before a number, and each developer shows you only its own sites.
Send MW, date, power structure and offtaker status.
We match it against sites and capacity on our desk, including ones that are never advertised.
You get the fits by email and we introduce you directly.
You never pay us. Providers cover it.
Your price is the same as going direct.
From 500+ providers. No sales calls, no long forms.
5,000+ clients helped.

See how we helped teams secure colocation with the right power, pricing, and providers.