100 kW to 5 MW · pricing for late 2026 and 2027

Wholesale Colocation Providers: 100 kW to 5 MW, Matched and Quoted Free

Wholesale colocation is power bought in blocks of about 100 kW to 5 MW and more, priced per kW per month, usually in a dedicated suite on a 3–7 year term with a one-time fit-out charge. For late 2026 and 2027 deployments, our October 2026 price index puts space and power at $200–250 per kW for 100–500 kW and $185–250 for 1 MW and up. The largest blocks on our November 2026 capacity list are in Virginia, Texas and Georgia.

Updated November 2026 · Bob Spiegel, Founder, QuoteColo

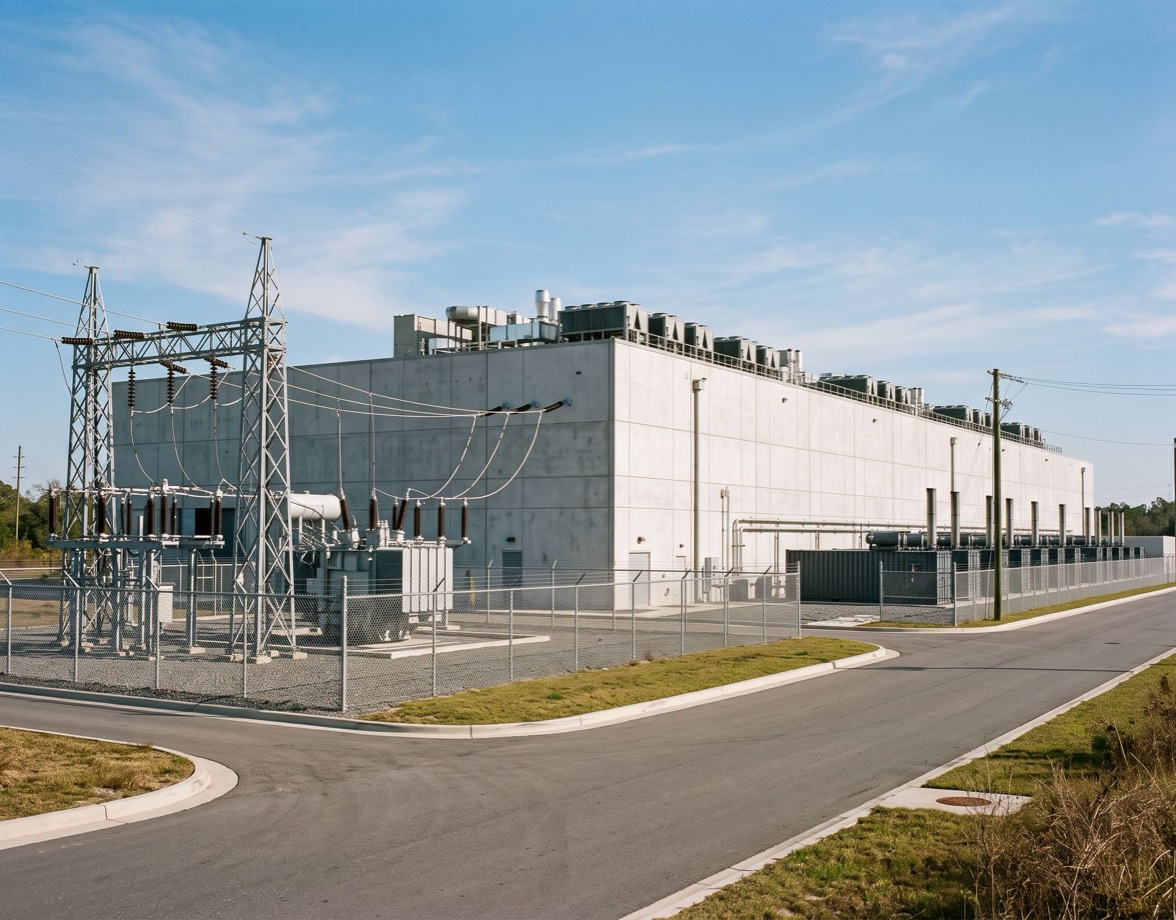
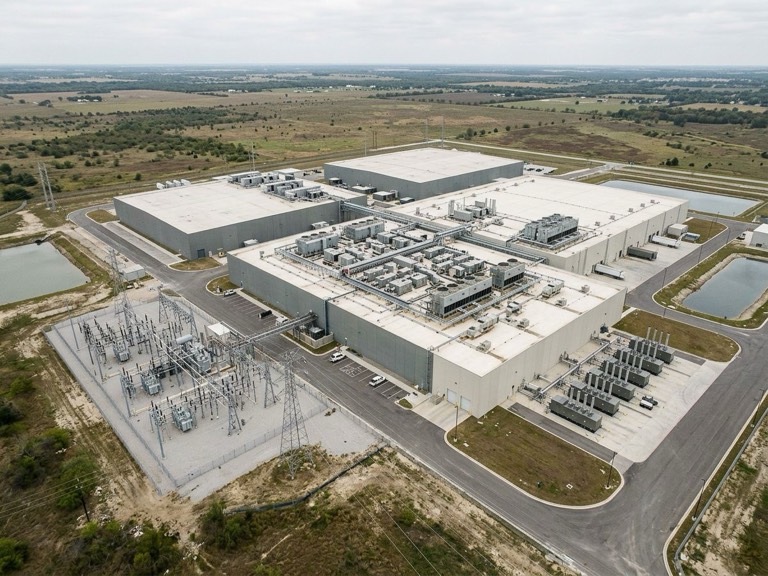
A wholesale data center building with rooftop chillers, fed by a high-voltage substation in front
Bob Spiegel

“Tell me what you’re deploying; I’ll come back with real options from a network built over 20 years.”

— Bob Spiegel, Founder, QuoteColo

From our desk, November 2026

$200–250
per kW per month for 100–500 kW (October 2026 index)
$185–250
per kW per month for 1 MW and up; $185 is the build-to-suit low end
72 MW
Largest listed block, Virginia
36 MW
Largest listed block, Texas

From Bob’s November 2026 price sheet and capacity list (listings, not confirmed offers) and the October 2026 price index (50+ provider responses). Prices are per month, space and power, unless noted.

What wholesale colocation is and what it isn’t

Wholesale starts at around 100 kW of committed power, where retail becomes expensive to run. From there you buy power capacity, not rack space.

What wholesale is

  • Committed power from about 100 kW to 5 MW and more, priced per kW per month.
  • A one-time fit-out charge (NRC) plus a monthly charge (MRC) for power, cooling and services.
  • Expansion options: more power later at pre-agreed rates, which retail contracts often don’t include.
What it isn’t

  • Retail. Below about 100 kW you’re buying a cage or a multi-rack product.
  • Hyperscale. Builds of 10 MW and up serve AWS, Azure, GCP and Meta; wholesale serves enterprises, SaaS platforms, AI and neocloud operators.

Typical wholesale colocation specifications

SpecificationTypical range
Rack count20–200+ racks
Power density5–80 kW per rack, depending on cooling
Total committed power100 kW–5 MW+
Connectivity10G–100G
Contract terms2–10 years (most 3–7)

For late 2026 and 2027 deployments, QuoteColo’s price index puts space and power at $200–250 per kW per month for 100–500 kW and $185–250 for 1 MW and up.

Who is actually buying wholesale colocation going into 2027

OrganizationSituationNeeds
Enterprise IT, consolidating from on-premClosing 3–5 aging on-prem sites and moving 200–500 racks. The board wants a 5-year cost model.A dedicated suite, a contracted power date, a 5–7 year term with CPI-capped escalators, an expansion path.
SaaS platform, cloud repatriationCloud bill past $1M a month. Needs 500 kW–2 MW deployed within 6 months.Power in a primary carrier market, fit-out in 90 days or less, cross-connects to cloud on-ramps.
AI / neocloud operatorGPU cluster for training or inference: 1–5 MW in a private suite, liquid cooling where the hardware requires it.DLC or immersion, A+B power at 30–80 kW per rack, dated power delivery, expandable to 10 MW over 24 months.
Content / streaming platformCDN sites of 200–500 kW each near major metros. Carrier diversity is non-negotiable.Options in 4–6 US metros at once, carrier-neutral facilities, consistent terms, an expansion rate card.
Managed service provider / hosting companyOwn infrastructure for enterprise customers: 250 kW–1 MW to make managed service pricing work.A $/kW that fits its margins, a 5-year minimum term, managed services run from the suite.
International company entering the US marketAPAC or European HQ needing a 100–500 kW US anchor site.A carrier-rich market, a provider used to international clients, USD pricing with a clear NRC/MRC breakdown.

Want these numbers for your own deployment? and we’ll reply with the providers that fit, with their prices.

The wholesale provider market: who operates at this scale

Three types of operator handle wholesale deals. In all three, current availability is rarely advertised; it comes through provider relationships, not search engines.

Operator typeExamplesWhat to knowBest for
Tier 1: hyperscale-adjacent operatorsEquinix, Digital Realty, Iron Mountain, QTS, CyrusOne, Vantage Data CentersPrimary markets, mature compliance documentation. Minimums often 10+ racks or 100 kW+ in primary markets; dedicated suites from 500 kW–1 MW.500 kW+, primary markets, 5–10 year terms, compliance-heavy environments
Tier 2: mid-market operatorsMid-market and regional operators, many of them in secondary marketsWhere most enterprise deals at 100 kW–1 MW get done. More flexible terms, often with capacity in secondary markets.100 kW–1 MW, secondary markets, 3–5 year terms, speed and pricing flexibility
Tier 3: power-first and purpose-built operatorsHydro-powered Pacific Northwest sites, energy-advantaged Texas sites, purpose-built AI facilitiesBuilt or repositioned for large, power-dense loads, often with custom cooling. Capacity moves through direct referrals, rarely through search.Large AI training deployments where $/kWh matters more than location

Provider tiers here are market segments, not Uptime Institute Tier ratings. Tier 1 names are examples of that tier, not a list of who has capacity now.

Wholesale colocation pricing: what $/kW actually looks like

Wholesale providers don’t publish rates, and market-by-market tables go stale within a quarter. These are the numbers we work from for late 2026 and 2027 deployments.

Planning bands for late 2026 and 2027 deployments

Deployment$/kW/month, space and powerWhat to expect
Under 100 kW$225–250A planning band; small racks and special configurations can differ.
100–500 kW$200–250The footprint many larger providers want right now.
1 MW and up$185–250Plan on 6–12 months, so 2027 blocks are being reserved now. $185 is the build-to-suit low end, not ready-now space.
Near-term listings$190–300Four listings of 200–800 kW on our desk, October 2026. Immediate capacity can price above the band.

QuoteColo price index, October 2026, 50+ provider responses. Planning bands, not market averages; bandwidth, cross-connects, IPs, setup and remote hands can be extra. NRC (one-time fit-out) is quoted separately and depends on cooling type; we include it in every wholesale comparison we send. The index has no separate band for 500 kW–1 MW: those deals are priced individually, and our October 2026 listings of 500–800 kW ran $190–240/kW.

On our November 2026 list, for late-2026 delivery

StateListed power$/kW/monthTermsAvailable
Colorado750 kW$25024 or 36+ months; air and liquidQ4 2026
Pennsylvania200 kW$20036 months; air200 kW listed as available now, non-redundant
Utah800 kW listed$24036 months500 kW listed as immediate; the rest Q4 2026

Space and power. Listings from our capacity list of November 4, 2026, not closed deals; provider names withheld. Listed power is not always one contiguous block, and listings change week to week. Waits for 2027 could be much longer, so reserve early.

What you’re actually negotiating in a wholesale colocation deal

Price per kW is only one line of the deal. These five terms decide the rest.

Deal pointWhat to know
Power delivery scheduleAsk first: it sets your timeline. For 1 MW and up, plan on 6–12 months; pre-built secondary-market space can be faster.
NRC vs. MRCOne-time suite fit-out vs. monthly power, cooling and services. Negotiate each separately; pre-built suites have a lower NRC.
Expansion optionsThe right to more power at pre-agreed $/kW rates. Agree it at signing; after you’re in, your leverage disappears.
Powered shell vs. fitted suiteA shell is raw space you fit out: less per kW, more CapEx. A fitted suite is ready for equipment.
Term length and exit rights2–10 years, most 3–7. Push for CPI-capped escalators (2–3%) and change-of-control provisions; early-exit costs depend on the contract and can include the unamortized NRC and the remaining term.

Wholesale colocation going into 2027: what’s actually happening

Deals happen offline, faster than the RFP.

Capacity in constrained markets is allocated through provider calls, not advertised online. By the time a formal RFP goes out, the best options are often committed.

Power, not space, is the binding constraint.

Ashburn, Silicon Valley and Chicago are short on power delivery. Large Ashburn blocks are often quoted 6–12 months out; secondary markets such as Columbus, Salt Lake City and Reno, and primary markets with heavy new construction such as Dallas, Phoenix and Atlanta, have better availability.

AI is redefining wholesale minimums.

Traditional wholesale ran at 8–10 kW per rack. AI deployments run 1–5 MW at 30–80 kW per rack, with liquid cooling where the hardware needs it.

Cloud repatriation is a major demand driver.

Many new wholesale buyers are enterprises leaving the public cloud. They have set budgets and board-approved CapEx, and need a shortlist in time for the window finance approved.

Why wholesale colocation is harder to procure than it looks

Most buyers try three of these first. At wholesale scale each one costs months, and the capacity you needed can be gone by the time you have comparable numbers.

THE DIY WAY

You search for wholesale colocation providers

You get the same Tier 1 names, and none publish availability or $/kW at scale. A week later you learn whether they have capacity. In Ashburn and Silicon Valley, the answer is increasingly no.

THE DIY WAY

You file a formal RFP to six providers

It takes months, not weeks: site surveys, power delivery schedules, NRC and MRC negotiations. By the time the responses are comparable, the capacity you needed for Q2 2027 can be gone.

THE DIY WAY

You rely on your network

You get three names you already know, at rates you could have found yourself. At 500 kW to 5 MW, capacity is allocated informally through relationships across many operators, not inquiry forms.

How it works

You send the specs. We find the options. You decide.

STEP 1

Send your requirements.

Tell us what you're deploying, where you want it, and when you need it. Send the specs you have; we'll help with the rest.

HardwareRacks & kWLocationStart date

Estimates are fine. No perfect RFP needed.

STEP 3

Take the next step. On your terms.

Like the options? Contact the providers directly. Need more detail? Call or email us. We're here to help, not push you.

  • Go directly to the providers you like
  • Ask us questions whenever you need

Get Wholesale Colocation Options

Free for buyers

Your price is the same as going direct.

All-in estimates by email

From 500+ providers. No sales calls, no long forms.

Trusted service since 2004

5,000+ clients helped.

Your request will be sent securely to QuoteColo.

The wholesale situations QuoteColo handles most

Your situationWhat we find
Need 100–500 kW soonMid-market operators with pre-built dedicated suites. 100–500 kW is the size many providers want right now.
Need 500 kW–2 MW in a primary marketTier 1 and Tier 2 operators with current availability. We ask them to confirm the power delivery date first.
Need 1–5 MW for AI / GPU at high densityPurpose-built or retrofitted operators with direct liquid cooling and power delivery in your timeframe.
Shopping primary vs. secondary marketBoth side by side: $/kW, power availability, deployment timeline and carrier ecosystem.
International team, first US deploymentUS options matched to your market and compliance needs, priced in USD with a clear NRC/MRC breakdown.

Case studies

See how we helped teams secure colocation with the right power, pricing, and providers.

Leonard Roszkowski

CEO Elemental Energy Solutions

Problem: Needed to source ASIC servers domestically. Skeptical about working with a new organization.

What we did: Connected them to buyers, sellers, and infrastructure partners across deployments. Removed procurement and logistics overhead entirely.

Result: Rapid organizational growth in a short period. Now uses QuoteColo as an ongoing procurement interface across hardware and infrastructure.

Noel Frutasio

CEO FSN Services and Communications

Problem: Regularly needed colocation space across multiple US states and time zones. Difficult to navigate the market without deep industry knowledge.

What we did: Defined requirements in one meeting, then delivered proposals with multiple carrier and data center options across every target market.

Result: Placed in 4 cities. Contracts signed quickly. Multi-state colocation needs resolved through a single point of contact.

Tim Mandell

DC Mining / MDI Access

Problem: Needed reliable options for crypto mining containers and equipment, along with industry partners who could support real deployment requirements.

What we did: Connected the project with relevant mining infrastructure and equipment resources through the QuoteColo network, simplifying the search and evaluation process.

Result: Gained a clearer path to suitable mining infrastructure, equipment and industry contacts without having to source every option independently.

5,000+

Clients helped since 2004

No Cost

to Buyers

500+

Worldwide providers

Quotes

in 48 h

FAQ — wholesale colocation

What is the minimum size for wholesale colocation?

Most wholesale operators set their minimum at 100–250 kW of committed power, which typically corresponds to 20–50 racks at 5–8 kW per rack, or fewer racks at higher density. Some mid-market operators will consider deployments starting at 50–100 kW if the term commitment is strong (5+ years). Below that threshold, you’re in retail colocation territory (dedicated cage or multi-rack product) rather than a true wholesale suite.

What does wholesale colocation cost per kW for 2027?

For late 2026 and 2027 deployments, QuoteColo’s price index (October 2026, 50+ provider responses) puts space and power at $225–250 per kW per month under 100 kW, $200–250 for 100–500 kW and $185–250 for 1 MW and up. These are planning bands, not market averages. Bandwidth, cross-connects, IPs, setup and remote hands can be extra. Near-term listings on our desk ranged $190–300 in October 2026. NRC (one-time fit-out) is quoted separately and depends on cooling type, so first-year cost per kW is higher than the monthly rate.

What’s the difference between a powered shell and a fitted suite?

A powered shell delivers raw space with power and cooling infrastructure to the suite boundary. Your team installs the rack infrastructure and internal cooling distribution. A fitted suite is delivered ready for equipment. Powered shell is cheaper per kW but requires more upfront CapEx and construction management. Fitted suites cost more per kW but compress deployment timelines and reduce your capital risk.

How long does wholesale colocation procurement typically take?

From initial inquiry to signed contract typically runs 2–6 months for wholesale deals. The longest variable is power delivery timeline: in constrained markets, you may sign a contract and wait 6–12 months or more for committed power to be delivered. In secondary markets with operators who have pre-built capacity, power delivery can be much faster. Understanding the power delivery timeline, not just the contract timeline, is the critical procurement question.

What contract terms should I expect in wholesale colocation?

Standard wholesale terms run 3–7 years, with some large deployments at 10 years. Some near-term listings offer 24- or 36-month terms. Annual escalators of 2–5% are standard; push for CPI-capped escalators. NRC is typically amortized over the term; early-exit costs depend on the contract and often include the unamortized balance. Expansion options should be negotiated at signing: the right to take additional power at pre-agreed rates, typically within a 2–3 year window. Change-of-control provisions are important because wholesale operator M&A is frequent.

Is wholesale colocation available for AI and GPU deployments?

Yes, from operators built for AI density: these deployments often run 30–80 kW per rack (versus 5–15 kW for traditional enterprise), with liquid cooling where the hardware needs it (rack-scale NVL72 systems are liquid-cooled; 8-GPU nodes can run on air) and A+B power at high density. Not all wholesale operators can support this; many were built for 8–10 kW per rack. Before shortlisting providers for GPU and training workloads, we ask them about rack density, cooling and power delivery dates.

How does wholesale colocation compare to building your own data center?

For most enterprises, wholesale colocation is significantly cheaper than a build-to-suit or owned data center when you factor in land cost, construction timeline, utility procurement, and facility staffing. The break-even point varies by location and scale. In high-cost markets (Silicon Valley, NYC), wholesale wins economically up to very large scales. The calculus also depends on time horizon: 3–7 years strongly favors wholesale; 10+ years starts to justify owned infrastructure analysis.

Why can’t I find wholesale pricing online?

Wholesale providers don’t publish pricing because every deal is negotiated individually based on power level, term length, cooling requirements, suite configuration, and market conditions. A 100 kW and a 2 MW deployment with the same operator can price differently, though our index shows the bands overlap across sizes; the bigger differences are availability and terms. This opacity is why wholesale buyers benefit from a referral service with current provider relationships. We know what comparable deals look like and can tell you whether a quote is at market or above it.

Get 2–4 qualified options in 48 hours

Free for buyers

Your price is the same as going direct.

You will get all-in price estimates by email

From 500+ providers. No sales calls, no long forms.

Trusted service since 2004

5,000+ clients helped.

Your request will be sent securely to QuoteColo.